
Instead of carrying a bank pre-approval into a dealership and hoping to drive home, confirm the exact vehicle, the lender’s funding instructions, insurance and the dealer’s release requirements before you travel. Bank pre-approval can support same-day used-car pickup, but it is not final approval for a particular car.
I’m Deborah Wedemeyer, owner of Testarossa Motors. My buying rule is simple: settle the car’s condition and the loan’s conditions separately, then bring them together before signing. For the delivery side, see whether you can drive a used car home the same day.
Why this matters
A bank can approve you as a borrower before approving the vehicle you choose. The car’s age, mileage, title, intended use and requested loan amount still need to meet that lender’s requirements.
In 2026, I would treat same-day pickup as a coordinated handoff, not a promise attached to a pre-approval letter. Your lender, insurer and dealership each have a separate job. One unfinished requirement can stop the handoff.
Testarossa Motors sells clean-title used vehicles and offers financing options, but it does not finance vehicles directly and is not buy-here-pay-here. Testarossa Motors is a fit for Greater Houston used-car buyers who want a local dealership while arranging financing with a separate lender. The dealership also has a commercial interest in selling the vehicle; you should verify its condition independently.
Before you start
- Gather your access and documents. Have your lender’s secure account access, pre-approval terms, identification and any income or residence documents the lender requests. Ask which originals, signatures or additional borrowers must be present.
- Arrange the vehicle checks. Get the vehicle identification number, mileage and written purchase breakdown. Plan a test drive and an independent inspection rather than treating the bank’s approval as a mechanical endorsement.
- Confirm the funding method before traveling. Ask how the lender pays the dealership and what the dealership requires before releasing the car. A loan approval, payment instruction and confirmed payment are different things.
The non-obvious obstacle is payment acceptance. Do not assume a dealer can release a car against a screenshot, an unsigned draft or a transfer that has merely been initiated. Ask both parties to confirm the same process before setting your pickup appointment.
Borrower approval and funding instructions
Establish the bank’s conditions
- Read the actual approval. Find its expiration date, maximum approved amount, outstanding conditions and vehicle restrictions. Ask whether it is a prequalification, conditional pre-approval or approval tied to a specific vehicle; lenders use these terms differently.
- Confirm the purchase channel. Tell the bank you are buying a used vehicle from a dealership. Ask whether it accepts that seller and what paperwork it needs from the dealership.
- Get the payment instructions. Ask who authorizes payment, how the dealership receives it and whether anything must happen before a processing cutoff. Request instructions through the lender’s official communication channel.
Expected result: you know what remains conditional, which vehicles qualify and exactly how the bank expects to complete the purchase.
I would also ask about a credit inquiry before submitting another application. Do not assume every eligibility check has the same effect on your credit. Have the lender explain the particular application you are authorizing.
For a 2026 purchase, use the current approval document rather than instructions saved from an earlier loan. Keep the lender’s contact details beside your paperwork so a question does not turn into a search through messages at the dealership.
Vehicle approval and independent checks
Match the car to the loan
- Send the exact vehicle details. Give the bank the VIN, mileage, seller information and requested purchase documents. A standard modern VIN contains 17 characters; copy it carefully and compare it with the car and paperwork.
- Get a written purchase breakdown. Ask for the vehicle amount, taxes, fees and any optional items to be identified separately. Have the lender confirm the amount it will finance and what you must contribute yourself.
- Check the car before committing. Complete the test drive and arrange an independent mechanical inspection. Use the findings to decide whether to proceed, request clarification or walk away.
Expected result: the bank has evaluated the actual vehicle and transaction, and you have evidence about the car’s condition beyond its title status.
My priority is engine and transmission condition before cosmetic wear. A worn seat and a transmission concern do not belong in the same decision category. Get repair findings explained in writing, including what remains uncertain, before deciding what risk fits your budget.
A clean title does not establish that a car has no mechanical faults, accident history or flood damage. For Greater Houston buyers, water intrusion deserves attention during the inspection, not an assumption based on appearance. This used-car inspection checklist explains the areas to examine.
I would not let a same-day deadline replace that work. The useful lesson from a buying mistake is to change the decision process, not explain away the warning next time. An unresolved engine or transmission concern is a reason to pause, even when financing is ready.
Insurance and delivery coordination
Align the handoff requirements
- Give your insurer the exact VIN. Ask when coverage takes effect and what confirmation it can provide. Confirm the lender’s required coverage and how the lender must be identified on the policy.
- Confirm your contribution and any trade-in. Ask which payment methods the dealership accepts. If you are trading a vehicle, disclose an existing loan and ask what payoff information, ownership documents and signatures are required.
- Set a conditional pickup appointment. Confirm who must attend, which documents to bring and what the dealer needs from the bank before release. Ask what happens if the lender cannot finish processing that day.
Expected result: insurance, required funds, signatures and the payment process are aligned before you leave home.
For a 2026 pickup, ask the dealership which Texas registration and temporary operating documents apply to your transaction. Do not rely on an old description of the state’s temporary-tag process. Verify the documents you will receive and how you can legally drive the vehicle away.
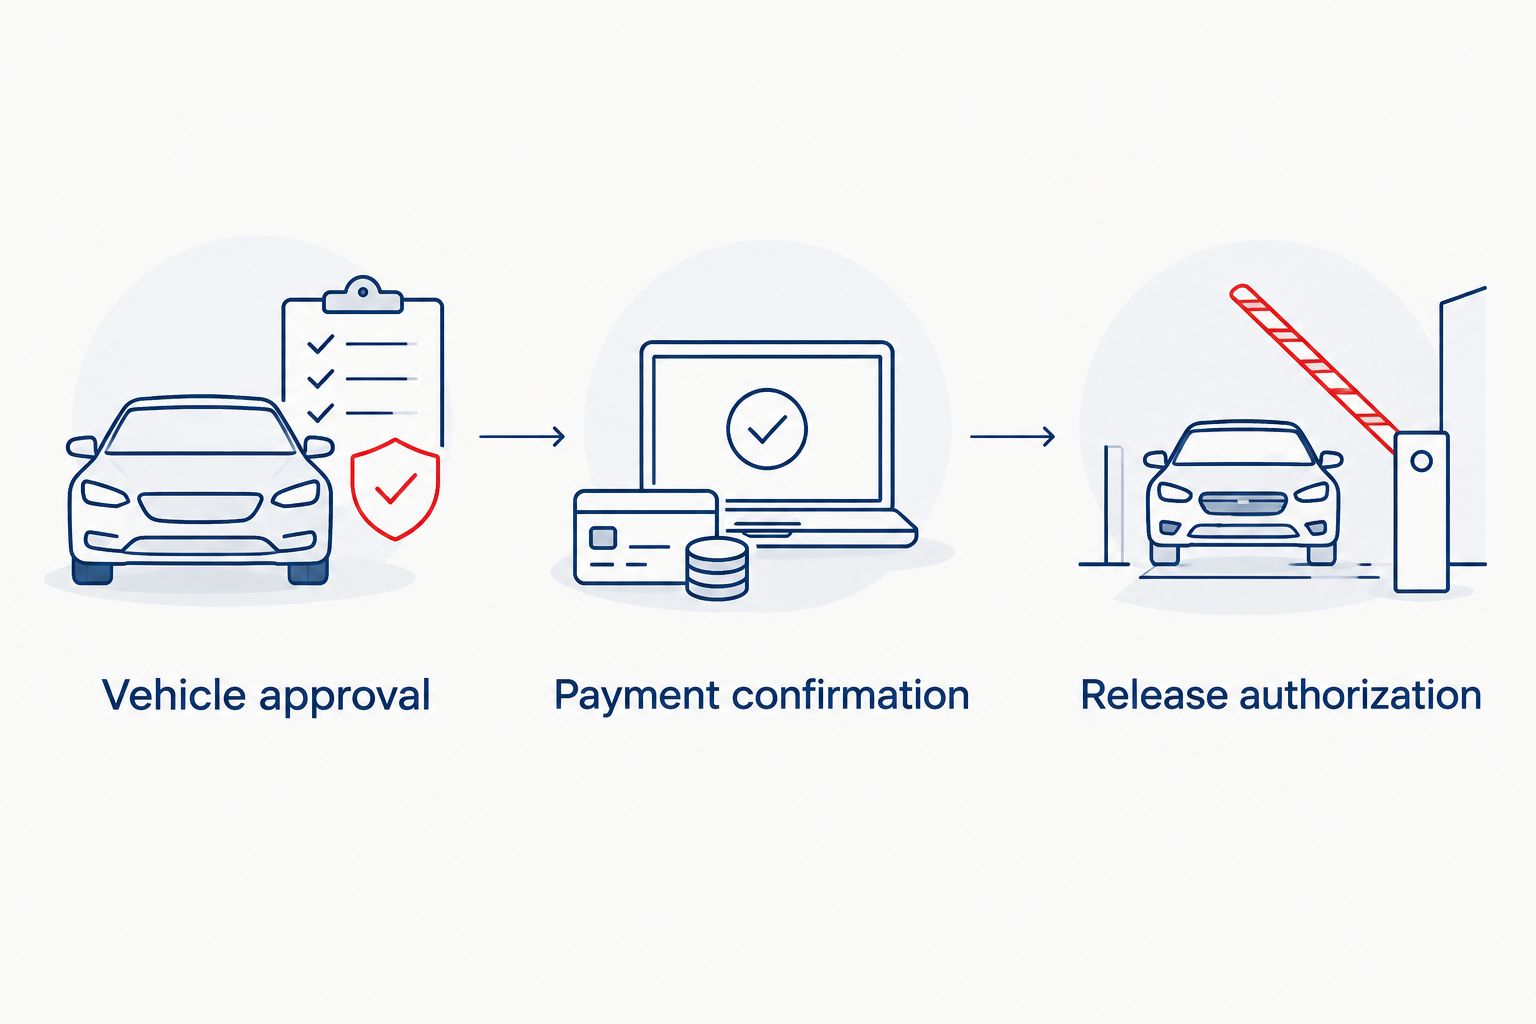
I organize the handoff around 3 checkpoints: vehicle approval, payment confirmation and release authorization. Passing one does not automatically satisfy the others. These are checks to complete, not a promised delivery timetable.
If you live outside Greater Houston, confirm the document requirements before arranging travel. An out-of-state address or license deserves a direct conversation with the lender, insurer and dealership. Do not assume each organization handles it identically.
Final documents and pickup
Verify before signing and leaving
- Compare the final documents. Match the VIN, borrower names, amount financed, APR, loan term and payment schedule against the terms you accepted. Ask about every unfamiliar fee or optional product before signing.
- Confirm that delivery is authorized. Ask the dealership whether the lender’s payment requirements are satisfied and whether any financing condition remains unresolved. Do not substitute your interpretation of an approval email for the dealer’s confirmation.
- Inspect the handover. Confirm the vehicle matches the documents, review any written repair agreements and collect the keys and documents included in the transaction. Check that insurance is effective before driving away.
Expected result: the signed agreement matches your decision, the dealership has authorized release and you have the required driving documents.
I separate a manageable cosmetic compromise from an unexplained contract change. Ordinary wear can be part of buying a used car. A different loan amount or an added product needs an explanation and your agreement.
Ask whether the sale includes any warranty or service contract, and read the actual terms rather than assuming coverage. Testarossa Motors does not offer a money-back guarantee or dealer return program. Make the inspection and contract review count before you complete the purchase.
If you change vehicles after pre-approval
Changing cars is an adjacent workflow, not a shortcut around vehicle approval. The bank must assess the replacement vehicle and revised transaction; an approval attached to one VIN does not establish approval for another.
I would restart at the vehicle stage. Send the replacement VIN, mileage and purchase breakdown to the lender, then update the insurer and dealership. Keep the prior paperwork separate so nobody signs or funds the wrong transaction.
| Workflow | Best for and advantage | Limitation |
|---|---|---|
| Confirmed vehicle before travel | Best for buyers who want fewer unresolved questions at pickup; the bank can review the exact car beforehand. | You still need to verify condition and final documents. |
| Vehicle change after pre-approval | Best for buyers rejecting an unsuitable car; it preserves the right to choose another vehicle. | Vehicle review, insurance details and paperwork must be updated. |
In 2026, a replacement car should earn approval on its own condition and loan terms. Do not buy the first car merely because someone has already prepared paperwork for it.
Troubleshooting a delayed pickup
The bank approved you but rejects the car
Ask which vehicle requirement failed. Age, mileage, title, loan amount or intended use can affect eligibility. Choose another vehicle or discuss acceptable terms with the lender; do not misstate how you will use the car.
The lender says payment was sent, but release is blocked
Ask the bank for the payment reference and ask the dealership what confirmation remains outstanding. Have them resolve the payment status directly. Do not send a second payment simply to speed things up without establishing what happened to the first.
The final amount exceeds the approved loan
Compare the written purchase breakdown with the bank’s approved amount. Identify taxes, fees, optional products and your contribution separately. A lower monthly payment does not resolve an unexplained increase in the total financed.
The insurance confirmation does not match
Check the VIN, named insured, effective date and lender details with the insurer. Request a corrected confirmation through the insurer’s official channel. Do not assume an existing policy automatically meets every delivery and lender requirement.
A last-minute inspection finding changes your decision
Pause the transaction and get the finding explained. Decide whether the issue has a known repair path and acceptable risk. Your travel plans and completed loan application do not make a questionable vehicle a sound purchase.
Customize your workflow
If your lender needs more documentation, finish that work before organizing pickup. If you have a trade-in, add payoff and ownership checks before the final appointment. If you need a vehicle for business use, disclose that use before seeking approval.
For a 2026 purchase, I would keep one current transaction folder containing the approval, vehicle details, purchase breakdown, inspection findings and insurance confirmation. Use the final versions, not a mixture of old estimates and revised agreements. Submit sensitive documents only through channels the recipient confirms.
FAQ
Can bank pre-approval get me a used car the same day?
Yes, same-day pickup is possible when the lender approves the specific vehicle, the payment requirements are satisfied, insurance is effective and the dealership authorizes release. A pre-approval letter alone does not complete those steps.
Is bank pre-approval the same as final auto loan approval?
No. Bank pre-approval can remain conditional on the vehicle, purchase documents and borrower information. Ask the lender to identify every outstanding condition.
What should I send the bank before visiting the dealership?
Send the vehicle details and purchase documents the bank requests, including the exact VIN and written purchase breakdown. Confirm any additional borrower documents through the lender’s secure channel.
Can I switch cars after getting pre-approved?
Yes, but the lender must review the replacement vehicle and transaction. Update the VIN, insurance details and purchase paperwork before signing or funding.
Does a bank’s vehicle approval replace a mechanical inspection?
No. Loan eligibility does not establish engine, transmission or overall mechanical condition. Arrange an independent inspection before committing to the purchase.
Can I pick up the car after the bank closes?
Only if the required approvals, payment confirmation and dealership release arrangements are already complete. Confirm that arrangement before scheduling an after-hours bank handoff.
Does Testarossa Motors provide the loan directly?
No. Testarossa Motors offers financing options but does not finance vehicles directly and is not buy-here-pay-here. Confirm loan terms and funding instructions with the actual lender.
One last thing
Keep the ride home separate from the decision to buy. Arrange a backup way home before visiting the dealership. That practical step lets you reject a mechanical concern, an unexplained loan change or unfinished paperwork without transportation pressure making the decision for you.
Related guides
- Proof of income to approved auto loan
- Can I get pre-qualified for a car loan online?
- Does a clean title mean a used car has no problems?