
 Buying Guides · Financing and Credit
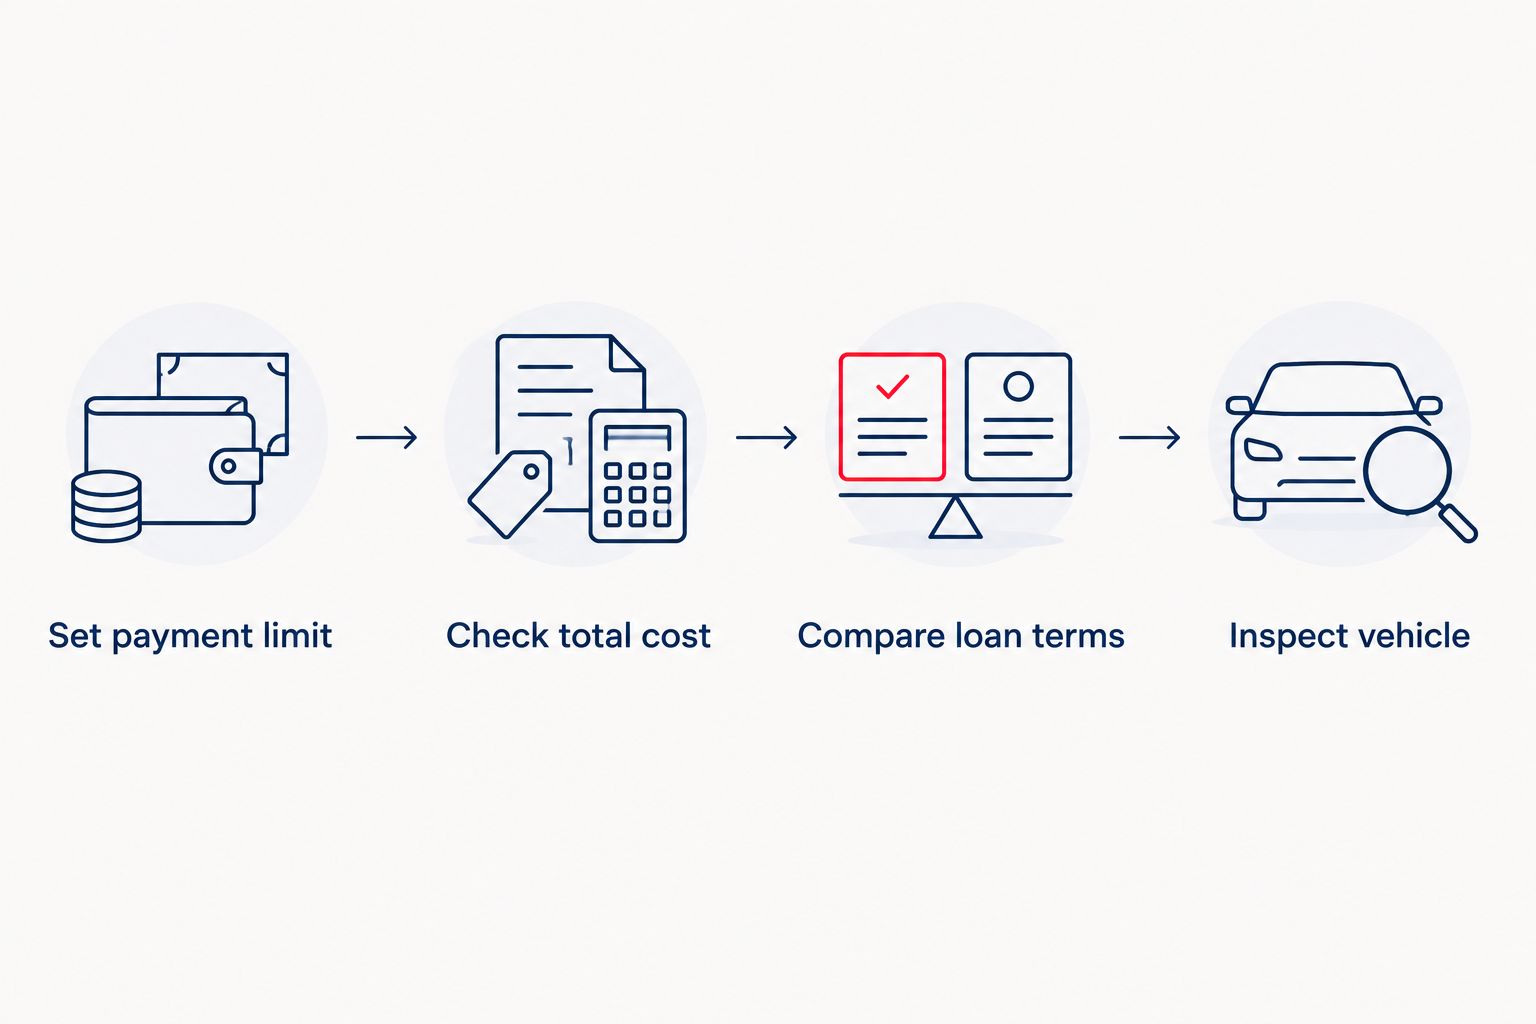
With a bruised credit file, the useful question isn’t “which car is best?” It’s “which car will a lender finance at a payment I can still make in month 40?” That changes the shopping order. You figure out the loan the vehicle has to fit inside, then pick between a commuter car, an SUV or a truck, and only then fall for a specific one.
This guide works through it in that order, with a worked loan example, the questions that tell a straight dealership from an expensive one, and what changes when you need a truck instead of a sedan.
What a lender looks at before it looks at the car
At Testarossa Motors the financing comes from outside lenders, typically 575+ credit, and approval is never guaranteed. There’s no buy-here-pay-here setup on our lot: we don’t lend our own money or collect your payments. So the lender’s view is the one that counts, and it usually comes down to four things:
- Your credit history, including how recent the late payments or collections are.
- Income you can document. Pay stubs, bank deposits, or benefit letters.
- Stability. How long you’ve been at your job and your address.
- The loan compared with the vehicle. Asking to borrow far more than a car is worth makes any file harder to approve.
Only the last one depends on the vehicle, and that’s the one you control on the lot. A cheaper, simpler vehicle shrinks the loan, and that can matter as much as the score itself.
Financing
See what you may qualify for
Apply online in one sitting. A real person at our League City lot reviews every application and sends it to outside lenders.
— Credit typically 575+
— No repossessions in the last 2–3 years
All financing subject to lender approval. Approval is not guaranteed.
Run the payment before you pick the vehicle
Here is a made-up example, not a quote. Say you finance $15,000 at 18% APR. The rate is only for illustration, because your actual rate is whatever the lender offers.
| Term | Monthly payment | Total of payments | Paid over the $15,000 |
|---|---|---|---|
| 48 months | about $441 | about $21,150 | about $6,150 |
| 60 months | about $381 | about $22,854 | about $7,854 |
| 72 months | about $342 | about $24,632 | about $9,632 |
Stretching from 60 to 72 months cuts about $39 a month and adds about $1,778 to what you pay overall. That trade is the main thing to understand before you sign anything. The “total of payments” line on a federal Truth in Lending disclosure shows it for your real loan, so find that box and compare it, not just the monthly figure.
Then add what the loan doesn’t cover:
- Insurance. Texas requires at least 30/60/25 liability coverage. Most lenders also require comprehensive and collision on a financed vehicle, so get a quote on the exact vehicle before you commit.
- Fuel. League City to downtown Houston is about 25 miles each way on I-45. At that distance, the gap between a 30 mpg sedan and a 17 mpg truck shows up every week.
- A repair cushion. Used vehicles need tires, brakes and batteries on their own schedule, not yours.
Commuter car, SUV or truck: three different loans
The commuter car
A clean-title sedan or hatchback is usually the smallest loan, the cheapest insurance and the lowest fuel bill. If your week is mostly a drive to work in Webster, the Medical Center or a refinery shift, this is the vehicle that leaves the most room in the budget. Check the engine, the transmission and the tires before anything cosmetic.
The SUV for passengers
An SUV makes sense when you’re regularly carrying kids, car seats or coworkers. You pay for that space in purchase price, fuel and tires. Choose the smallest one that seats your real household. A third row you use twice a year costs you every month.
The truck for hauling
A truck earns its payment if you tow, haul for work or need a bed every week. If you only need one a few times a year, renting is often cheaper than financing a bigger loan. Truck tires and brakes cost more, so ask for the tire date codes and brake condition in writing. If a truck is the plan, our guide to financing a used truck with bad credit in Houston covers it in more depth.
Six questions to ask any dealership
- Who is the lender, and can I see the offer in writing? A real lender’s terms come on paper. A verbal “you’re approved” doesn’t.
- Is the vehicle price the same if I pay cash or finance? It should be.
- Which add-ons are optional? Service contracts, GAP and other products should be things you can decline. Ask to see the amount financed with and without them.
- Can I have the vehicle inspected by my own mechanic? The FTC recommends an independent inspection on any used vehicle. A dealer who says no has told you something.
- Who services the loan and reports my payments? With a bank or credit union, you deal with the lender, not the dealership.
- What does the window Buyers Guide say? The FTC requires it on every used vehicle a dealer sells, and it says whether the sale is “as is” or comes with a warranty.
If the answers point to the dealer also being the lender and collecting payments weekly on the lot, you’re looking at buy-here-pay-here. Read whether buy-here-pay-here in Houston is really helping you before you go that route.
Coming from Webster, Friendswood, Dickinson or Alvin
This guide is written for shoppers within about 25 miles of Testarossa Motors at 521 State Hwy 3: League City itself, Webster, Clear Lake, Friendswood, Dickinson, Kemah and Alvin. If you’re driving in, bring proof of income, proof of address, your driver license and your insurance agent’s number. A refund or savings toward the down payment helps too. If a refund is your down payment, split it before you shop. For the application side, see used car financing in League City.
Financing
See what you may qualify for
Apply online in one sitting. A real person at our League City lot reviews every application and sends it to outside lenders.
— Credit typically 575+
— No repossessions in the last 2–3 years
All financing subject to lender approval. Approval is not guaranteed.
Bad-credit questions we get at the desk
What credit score do I need?
Our outside lenders typically look for 575+ credit, and below that we usually cannot place a loan. Above it, the score is only part of the file. Income, stability and the loan amount all count, and approval is never guaranteed.
Will a co-signer help?
A co-signer with stronger credit can change what a lender offers. They become fully responsible for the loan, so they should read the contract as closely as you do.
Should I pick a cheaper car just to get approved?
Pick the cheapest vehicle that does the job you actually have. A smaller loan helps approval and keeps the payment affordable once the excitement wears off.
Is a longer loan a bad idea?
Not always, but compare the total of payments for each term. In the example above, the 72-month loan costs about $1,778 more than the 60-month one.
Call (281) 332-6568 before you come in and we’ll tell you what paperwork the lenders usually ask for, so the trip isn’t wasted.
Deborah Wedemeyer runs Testarossa Motors, a used-car business on Hwy 3 in League City since 1995, with 18,000+ Texans served.
Where these facts come from
- FTC, Buying a Used Car (Buyers Guide, independent inspection): https://consumer.ftc.gov/articles/buying-used-car-dealer
- CFPB, Truth in Lending disclosures (amount financed, total of payments): https://www.consumerfinance.gov/ask-cfpb/what-is-a-truth-in-lending-disclosure-for-an-auto-loan-en-787/
- Texas Department of Insurance, auto insurance minimums (30/60/25): https://www.tdi.texas.gov/pubs/consumer/cb020.html
- Payment table: standard amortization math on a hypothetical $15,000 loan at 18% APR